Woodstock Jag
-
Posts
4,129 -
Joined
Content Type
Profiles
Forums
Events
Blogs
Gallery
Everything posted by Woodstock Jag
-
Meet The Board Event - 27th August
Woodstock Jag replied to Fawlty Towers's topic in Main Jags forum
I am stating that you're talking a load of shite. -
Meet The Board Event - 27th August
Woodstock Jag replied to Fawlty Towers's topic in Main Jags forum
1. Woodland Jag isn't a thing. 2. No, it was always the case that other shareholders could cooperate to oppose a special resolution. Nothing new. 1. Woodland Jag isn't a thing. 2. No it wasn't stated that "those with over 5% are now Consulted on Key decisions". You have again engaged in total fabrication. Stop making things up. -
Meet The Board Event - 27th August
Woodstock Jag replied to Fawlty Towers's topic in Main Jags forum
Important technical point here. I think you may have misunderstood what Sandy said on this. He didn’t say the cash buffer was £175k. He said the cash position improved by roughly that amount over a 12 month period. The cash in the bank is much higher than that, though you’d expect it to be at this point in the season. -
The weak point last night was the central midfield. Completely lost the battle to control possession in the middle of the park in the second half. Shinnie had them in his pocket. Frustrating as until last night I’d have said midfield was where we had more variety and depth. It’s pretty clear our first choice midfield isn’t yet ready to see out 90 minutes as well which doesn’t help. I wondered whether, rather than take Samuel off in a game like that, it makes more sense to bring Watt into the midfield. Not sure the GMS sub was the right one either unless Drodz had a knock?
-
That’s twice now this week I’ve planned to drop by Jaconellis in regular hours but it’s been shut. Anyone know if this is a temporary thing?
-
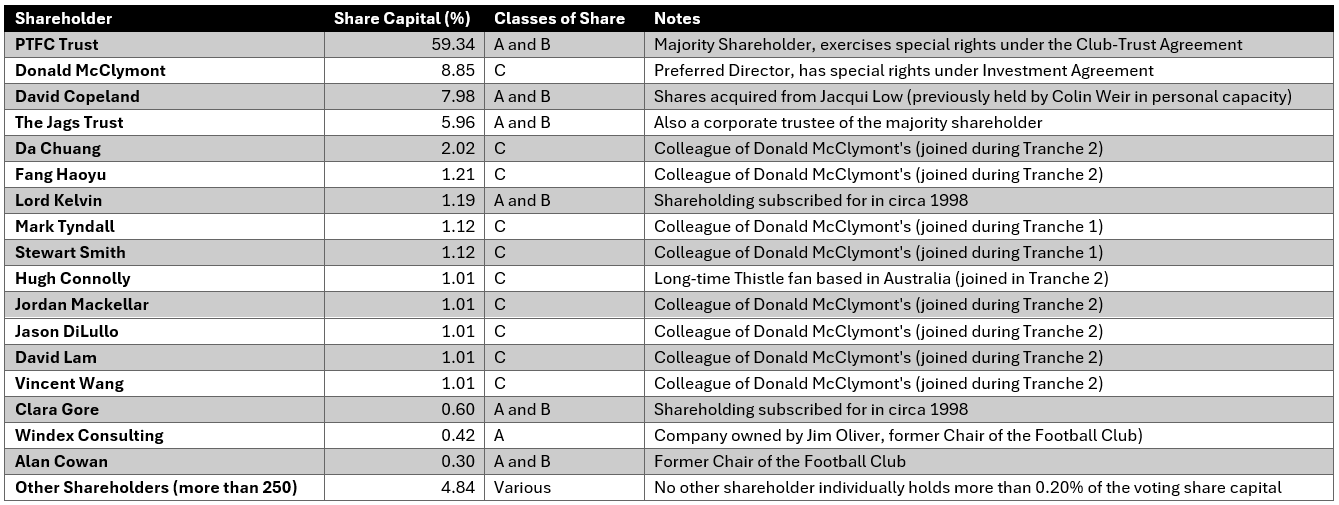
Not quite right. But for a very subtle and forgivable reason that could easily be missed comparing between the Confirmation Statements. £60k of the £500k of Tranche 2 was only formally incepted relatively recently. So while I think it was 8.08% for a while, the relevant shareholding is now worth slightly under 8% once those extra shares are taken into account. Tables for reference, any errors mine etc.
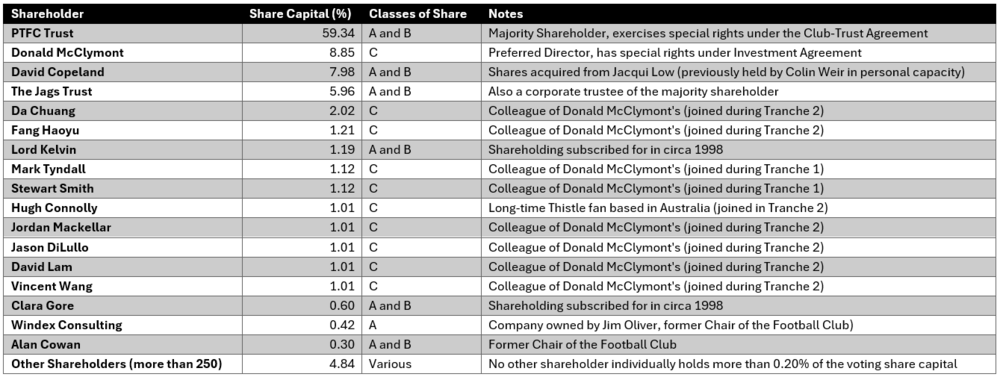
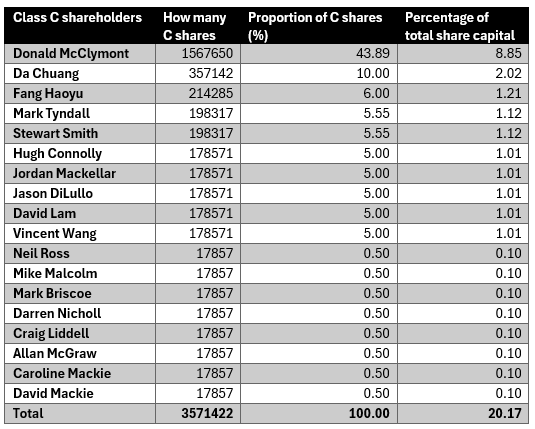
-
No. You have misunderstood. The reason "shareholders" is in plural is because there are two fan groups with shareholdings. Those two fan groups are aligned in terms of the goals they have for the football club. Fortuitously, those goal also appear to be aligned with those of the other main shareholders (i.e. those with materially significant shareholdings with practical consequences, not those with nominal shareholdings). The majority shareholder and other aligned shareholders want a senior leadership group in place at the football club (Club Board directors, senior staff) who are aligned to those goals: "shared goals". No, the 5% threshold is simply an example of one in company law that makes some shareholdings more significant than others. No, this is where you go wrong and have misunderstood. Director appointments are made by the Club Board. The directors of the Club Board propose director appointments, by Club Board resolution. Director appointments, the appointment of Preferred Directors aside (i.e. apart from Donald McClymont) are made subject to the consent of the majority shareholder, under the CTA. The Club Board therefore has to consult (and gain the agreement of) the trustees before proposing the appointment of any director. Additionally, the Preferred Director, under the Articles of Association and Investment Agreement, has a veto over board appointments that would take the size of the Club Board beyond 8 directors. The shared goals are set out in the strategic plan, business plan and budgets proposed by the Club Board and approved by the trustees from time to time under the CTA. Go and read section 303 of the Companies Act 2006. It says that 5% of voting share capital can summon an extraordinary general meeting. That's all it says. They don't. I didn't say they did. You suggested they did. Erroneously. No, you are completely misunderstanding what I said. I did not say that other shareholders are consulted on Club Board appointments. They aren't. The Club Board proposes board appointments, and it consults and seek the consent of the trustees to them. And if a Club Board appointment would take the Club Board over 8 members, Donald McClymont then has a veto. By virtue of his shareholding. The individual members of the Club Board indicated to the trustees their willingness (or otherwise) to serve as directors beyond the AGM. The trustees appraised their performance and suitability and reached a view about which directors should continue and which ones should not. This was communicated to the Club Board, and there were follow-on discussions about the wider implications of this (including thinking about further board recruitment beyond the AGM). Individual directors then took a view on their own positions based on those discussions. And the trustees voted to reappoint all of those directors who then sought reappointed at the AGM itself. That was the process. No it isn't. You have confused two different assertions. There is the assertion I made, which is that a Club Board has to take into account shareholders representing more than 5% of voting share capital differently than those with much smaller shareholdings, because they have certain statutory rights, and this makes it desirable to have a positive relationship with those shareholders. And then there is the assertion you made, which was totally made up, which is that somehow minority shareholders have some special consultation role on Club Board appointments. Which is false. The majority shareholder takes decisions as it sees fit and those minority shareholders vote at general meetings as they see fit. Because it doesn't exist you've literally just made it up. Because it doesn't exist you've literally just made it up. They weren't involved in the process you've literally just made it up. They weren't involved in the process you've literally just made it up.
-
There is no "rule regards Shareholder input to Governance". The Companies Act 2006 confers specific powers on shareholders comprising 5% or more of the voting share capital of all limited companies. There is no rule. There is the Companies Act 2006, section 303, passed by Parliament. You have. section 303 of the Companies Act 2006.
-
Generally speaking, if a match takes place between 2.45pm and 5:15pm (UK time) on a Saturday it is against SFA rules for it to be broadcast live to a domestic audience. This actually even includes the broadcast of games from other countries (eg El Classico can’t be broadcast on a Saturday at 3:15pm to UK television audiences). The rule exists to encourage in-person attendance at football matches and (IIRC) each football association technically applies to UEFA to formally approve their respective blackout times. There are exceptions for certain Saturdays. For example, it tends not to apply during international weekends, or to certain domestic cup weekends. There is sometimes greater flexibility around the fixtures between Christmas and New Year as well. It also technically doesn’t apply if less than half of the games in the country’s top two divisions are scheduled to kick-off during the blackout period on that weekend.
-
No argument here on that. No that’s not what I said. You are overinterprering it. It was an acknowledgment that the PTFC Trust is not the only individual shareholder, in governance terms, that is relevant to what the Club Board can, and cannot, do, or in relation to statutory thresholds for the exercise of minority shareholder rights. Good luck with your efforts to summon an EGM. I am sure you’ll get the 200 or so proxies you need.
-
All set out transparently in the Fans' Guide to the Tranche 2 Investment almost 2 years ago. It is entirely a matter for The Jags Trust how it votes at General Meetings. They are a separate shareholder in their own right. It is important. At a football club the key decision-makers are not just the Board of Directors. A lot of operational and strategic decisions are delegated to senior managers, on both the footballing and non-footballing side. We literally have a Sporting Director who deals with player recruitment and how the wider football budget is spent. The Club has at various points had a CEO/GM role to oversee and develop the non-footballing part of the business day-to-day. Those people are important ones for any Club Board member to be able to work effectively with, because they will be the people giving effect to their strategy or plan. In any organisation you would seek to appoint directors who can work constructively with and get the best out of the people in those positions. Similarly, it is important that a Club Board member is able to work effectively with those shareholders (plural) who need to agree to the things they want to do before they can be done. In the context of the finances of the football club, we know that both the Club-Trust Agreement and the Investment Agreement are relevant to this.
-
I didn't say they should. I said that any assessment of the suitability of a candidate for the Club Board should take into account someone's ability to work with the senior leadership group. Note, the word "leadership", not "management". You actually changed that subsequently. The senior leadership group at the Club clearly also includes (in addition to the Club Board and the senior managers who run the club day-to-day) the two corporate trustees, as the PTFC Trust has a veto over the Club's adoption of any budget, strategic plan and business plan. Well given that there are two fan group-controlled shareholdings that's probably a pretty solid start for explaining why I used the plural "shareholders". One of the other errors you made in your earlier post was to suggest that the PTFC Trust holds almost 70% of the shareholding in the Football Club. It's nowhere near that. It's just over 59%. And The Jags Trust holds just under 6%.
-
Okay now I know you definitely haven't read it! Anyone who holds less than 50% of the shares is a minority shareholder, Jim. But a shareholding of 5%, for example, can force the calling of an extraordinary general meeting of the company. A combined shareholding of 10% could, of course, force a poll vote at a general meeting or demand an audit. A combined shareholding of 15% could (theoretically) block a change to rights classes of share. A combined shareholding of 25% could block a special resolution. So it is, in fact, important to understand which individual shareholders, or combination of shareholders, are likely to be able to meet those thresholds. It's not 10% or nothing. Edit to add: it is also relevant to consider the rights of minority shareholders in light of the rights conferred by specific classes of share. In some instances a Class C shareholder will have more rights, for example, than a holder of the same voting share capital held in Class A and/or B shares. This was explained at length earlier in the thread. Not the bit you got wrong. Any person holding more than 5% of the total voting share capital at the football club. Nothing of the sort. The phrase "senior leadership group" was used collectively to describe both the Club's directors and its employed senior managers.
-
It will be very obvious to those who have read the Confirmation Statement who hasn't.
-
You don't need to be forensic to obtain the basic information about who the shareholders are at the Club. If, for example, you were to download the latest Confirmation Statement, and then to upload it to Google AI with the instruction: You would find it educational.
-
Thanks again to everyone who takes part in this. A lot of a little makes a lot!
-
I would suggest that you look at the most recent Confirmation Statement on Companies House. You are mistaken on several basic factual points.
-
Will the club shop be opened for tonight's game
Woodstock Jag replied to 1876's topic in Main Jags forum
Opening Hours are: Tuesday-Friday - 10am to 5pm Saturday - 10am-1pm (when there isn't a game at Firhill) and until kick-off and then open again for half an hour after full time (when there is a game at Firhill) As advised on the launch news item.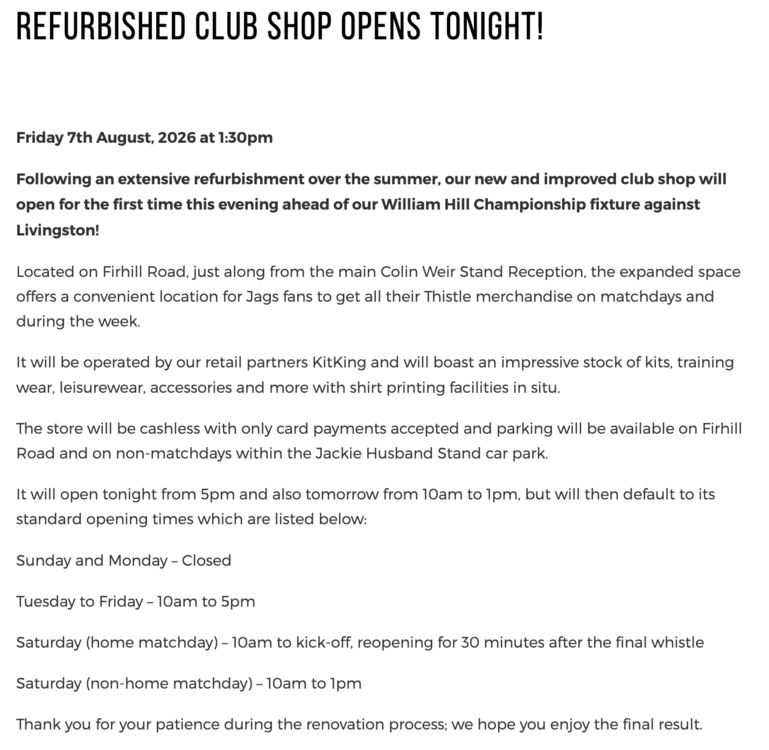
-
This is where we fundamentally differ Jim. I don't think being quite so casual about Club Board appointments as to say just appoint people and "don't worry it doesn't matter what process you use, half of them will be good and half of them will be bad" is right. I think that, with the right process, you reduce the likelihood of recruiting people that will have a net negative impact. You get better at weeding out people who Can't stick out a 2-year term. Talk a good game but won't deliver. Are going to fall out with everyone. Want to be involved for the wrong reasons. Are not aligned to the shared goals of the main shareholders and the senior leadership group.
-
I wasn't talking about any particular director. You're desperate to spill the beans about all the people you've told the trustees they should be appointing. It's a bit unedifying. I was making a general point that, just because someone comes highly recommended by Jim Alexander because they "ran a successful business", or for that matter by anyone else, doesn't mean that they're suitable for appointment to the Partick Thistle Football Club board of directors. As with any properly functioning organisation there is a process, and it exists for a reason, and is there to be followed. Interpersonal relationships are important. The trustees need to be satisfied that any Club Board appointments aren't going to lead to people on the board falling out with one another, and are going to lead to net positive contributions to the work of the Club Board as a whole. The fan owners would expect nothing less.
-
There was a falling out at Club Board level. His fellow directors took steps to remove him. In particular, there was a break-down in the relationship between him and another Club Board member. It played out very publicly as allegation and counter allegation were traded (including by Mr Creevy at other Club Board members, on Facebook - not very edifying). This situation dragged out as the trustees attempted to mediate between the parties. Eventually it was clear that there was no prospect of Mr Creevy returning to the Club Board without triggering resignations of other Club Board members. The trustees therefore, reluctantly, exercised their powers formally to remove Mr Creevy, to bring the dispute to an end. The director he particularly publicly fell out with stepped down from the Club Board a few months later. As is so often the case at organisations like a football club, the reasons for directors leaving are almost always specific to interpersonal dynamics, and people falling out with one another. One reflection I have having been a TJF board member for just over 4 years now is that on far too many occasions, the departure of Club Board members has been triggered by them falling out with one another. Unfortunately, influential as the trustees may be, we can't force people to work with one another. We inhabit a reality where we end up mopping up the tedious interpersonal nonsense of others. This is also why the ability of people to work collegiately, and to stick the course, is particularly important. It helps explain why we might, for example, want to have a shortlisting exercise for Fan Rep directors, allowing us to interrogate a little someone's suitability for the role and their willingness to put in a 2-year shift. It's also why we might be cautious about appointing people to the Club Board simply because Jim Alexander has recommended them to us and said they're brilliant because they've "run a successful business".
-
There was no shareholder vote on Nett Zero. You're talking nonsense. What happened was that a shareholder (you) called for a Nett Zero budget and a representative of the PTFC Trust (me) asked the then Chair of the Board whether he would consider conducting a zero-based budgeting exercise to identify opportunities to cut costs. He said "that's a good idea we're happy to look into that". And shortly thereafter he tasked the Finance Working Group, of which you were a part, to do that exercise. Bullshit. This didn't happen. That you should probably have a better basic comprehension of what happened than what you're now saying, given you were privy to the exercise.
-
You're distorting, again. TJF called on the Club Board to engage in a zero-based budgeting exercise, to better understand what existing spending commitments were considered core and essential to the Club, what ones were considered strategically desirable, and what ones were considered to be discretionary. The purpose of such an exercise was to inform the budget choices the Club Board would make, and to provide both the Club Board and the trustees with a better understanding of what changes would be necessary to deliver break-even budgets going forwards, assuming no significant changes in revenue generation. You, as part of the finance working group, were tasked with undertaking that exercise. You provided some documents to the Club Board in connection with this (some, but not all, of which were then shared with the trustees). That work, which you took part in under an NDA, then informed both the Club Board's budget proposals in the summer of 2025, and influenced the trustees' thinking about the acceptability (or otherwise) of earlier iterations of those budget proposals.
-
So this isn't the bullet you think it is. Class C shares - preference, but not really While Class C shares are (technically) preference shares, the specific preference shares in this case: (a) do not take priority over Class A or Class B shares in the event of winding-up or insolvency (Article 29.2.3 says it ranks pari passu with other shares) (b) do not come with special dividend rights (Article 29.2.2 says they are not entitled to participate in the distribution of profits of the company) Why are they preference shares? There are essentially two reasons that they are preference shares. Reason 1 - Redemption The first is to allow for the redemption mechanism, which does not apply to Class A or Class B shares (alluded to in Article 29.2.4). In the event that the Club sustains a significant improvement in its balance sheet, such that the cash position significantly exceeds £2 million, the Class C shares can gradually be redeemed, meaning that their holders are diluted from the excess. In the event that Thistle sells a player for Lennon Miller amounts of money, or the Club runs substantial surpluses for several years, Donald McClymont and his colleagues will begin to get some of their money back, and their shares will go back to the Club. Seems a pretty fair trade, if you ask me. Reason 2 - Non-dilution The second is to prevent Class C shareholders from being diluted in the event that further shares are issued in the company. For example, Donald McClymont, Mark Tyndall and Stewart Smith all exercised their pre-emption rights in relation to Tranche 2, so that their percentage shareholding in the company would not be reduced as a result of others joining in with Class C shares. So they (paid so that they) avoided being diluted. That's not a privilege offered (on paper) to Class A and B shareholders, but in practice anyone could have chosen to pony-up and to participate in that second Tranche (about 10 or so people chipped in for £5k segments). What other rights do Class C shares confer? Beyond those core protections, the other special rights of Class C shares are really mundane. If you hold (a) the majority of the issued Class C shares or (b) more than 1,250,000 Class C shares (at the moment that would mean you are essentially a more than 7% shareholder in the company) then you gain the right to be/nominate a Club Board Director. These are known as "Preferred Directors". Who is able to be a Preferred Director? Only Donald McClymont is in a position to do this. In theory, 5 or more of his 1-2% each investment colleagues could transfer all their shares to one person and that person could also gain these rights. However, any such share transfer would be subject to Club Board approval. What can a Preferred Director do? A "Preferred Director" can: block a voluntary liquidation, dissolution or wind-up of the company block any resolution of the company that would alter the rights of Class C shareholders block the issuing of any convertible security (i.e. a new share issue by the back door) block the Club from issuing cryptocurrency or blockchain assets block any dividend being issued block any share/equity compensation plan block any action that leads to the PTFC Trust ceasing to be the majority shareholder, unless the PTFC Trust has consented to it block the Club from lending money to people block the Club from borrowing more than £250k to any third party or lender block the selling off of major assets through a share or equity security block the appointment of a Director if it would have the effect of making the Club Board bigger than 8 people This list is similar to (but much shorter than) the list of things that the PTFC Trust can also veto under the Club-Trust Agreement. Crucially, these rights can only be exercised if the person in question has actually become a Preferred Director. Almost everything on this list is simply about preventing Class A and B shareholders from screwing over Class C shareholders by reducing the real-world value of their shareholding. It's dull. It's boring. It's not a conspiracy. So what can the PTFC Trust do? While the Investment Agreement/update to the Articles came before the Club-Trust Agreement, it sits alongside it. The CTA gives the Trustees the power to veto: changes to the share capital of the company changes to the stadium location or name changes to the official badges, logos or other devices etc the colours and styles of the Club's home strip changes to the name or official nickname of the Club or its status within the SFA or SPFL the purchase or disposal of any land or buildings by the Club entering into any lease of duration longer than 5 years secured borrowing unsecured borrowing (otherwise than in the ordinary course of trade) contracts at a cost of £50kpa or more, except for playing contracts (the threshold is lower under the Financial Stewardship provisions in periods of financial distress) Club Board recommendations for appointment or removal of Club Board members changes to the responsibilities or job description of the Chair, Chief Executive (or equivalent) or other Directors, subject to the Corporate Governance Manual dealing with those issues changes to the terms of reference of Club Board sub-committees changes to the Club's Articles of Association the Club Board's proposed budget, strategic plan and business plans changes to the capital structure of the company or its legal status the incorporation of any subsidiary of the company the extension of the Club's activities into any significant new business area, or to cease to operate in a significant existing business activity proposals to wind-up the Club or appoint an insolvency practitioner These powers, unlike Donald McClymont's/Class C rights exist without the need to have a director nominee. These are basic rights accepted to belong to the majority shareholder. And in addition there is a requirement that there will be at least two Fan Rep Directors unless and until otherwise agreed. Pulling it all together The notion that TJF, or the Trustees, somehow "call all the shots" is wrong because: we do not exercise day-to-day control over the Club or its operations, and this is done by the Club Board Donald McClymont's investment agreement means that some activities (particularly relating to the Club's finances and shareholding structure) require the consent of him, a minority shareholder But equally the notion that TJF, or the Trustees, actually have "no real say" is wrong because: the PTFC Trust is a majority shareholder (and ultimately has all the powers that come with that, but lacks the power to pass special resolutions without the support of major minority shareholders) the Club-Trust Agreement gives the trustees a veto over a range of major strategic decisions at the Club (some of which are in turn out-sourced to the PTFC Trust's beneficiaries through fan votes) any well-functioning Club Board will develop an approach to running the Football Club that is aligned to and compatible with the priorities of the majority shareholder, to the greatest extent possible, because they will know that they have obligations under the CTA